£249m Refinancing Backs Next Chapter for Manchester’s Landmark Square Gardens
Downing has secured a £249.2 million refinancing package for two major residential towers at its £400 million Square Gardens development in Manchester, marking another significant milestone for one of the city’s largest new living schemes. The financing, provided by Bank of Ireland, covers Acer and The Fernley, the two completed co-living buildings within the wider Square Gardens development in Manchester’s First Street district. Together, the buildings provide a major concentration of new rental accommodation, with the 25-storey Acer and 45-storey Fernley forming the first two phases of the development. Both buildings are now operational, demonstrating the scale of demand for professionally managed, amenity-led rental accommodation in Manchester. Designed by Manchester-based SimpsonHaugh Architects, Square Gardens represents a substantial addition to the city’s evolving residential landscape. The wider £400 million development has been conceived as a new urban neighbourhood combining high-density living with extensive shared amenities, landscaped spaces and public realm. Residents have access to facilities including a gym and wellness centre, co-working and meeting areas, social lounges, private dining spaces and extensive landscaped gardens and terraces. Sustainability has also formed an important part of the development, with measures including air source heat pumps, while the scheme has targeted BREEAM Excellent and EPC A ratings. The refinancing represents an important financial milestone following the completion and occupation of the two buildings. Savills Capital Advisors advised Downing on the transaction. Bay Downing, joint chief executive of Downing, described the deal as a landmark transaction for the business, highlighting the strength of the company’s portfolio and growing opportunities across the living sector. The deal is also significant for the wider UK residential market. Large-scale co-living and Build to Rent developments are becoming an increasingly established component of regeneration in major regional cities, combining new housing supply with extensive shared facilities and professionally managed environments. Square Gardens has been created using Downing’s vertically integrated approach, with development, construction and ongoing management delivered by the business. This has enabled the company to take the scheme from construction through to operation within the wider group. With Acer and The Fernley now completed and backed by £249.2 million of refinancing, Square Gardens is moving firmly from major construction project to established residential destination, reinforcing Manchester’s position as one of the UK’s leading markets for large-scale rental and co-living development. Building, Design & Construction Magazine | The Choice of Industry Professionals
Local government reorganisation review: Ensuring continuity in the face of uncertainty
Karen Carter, public sector director at public procurement specialist Pagabo, has shared her thoughts following the government’s announcement on its intention to review plans for local government reorganisation (LGR) and ensure alignment with its wider plan to rewire the state. Karen said: “This week’s announcement adds another layer of uncertainty for councils that have already spent months planning for reorganisation. Four areas have had their plans withdrawn, another 14 are paused pending review, and the 2027 elections will now be fought on existing boundaries. “For the teams involved, that’s a lot more work suddenly required without a clear landing point. But the fundamentals haven’t changed. Schools still need building, homes still need delivering, and estates still need maintaining. None of that waits for a structural decision in Whitehall. The risk in moments like this is that authorities press pause on everything, not just reorganisation, and lose a year of delivery to a decision that isn’t theirs to make. It’s vital that local authorities remember that successful transition will depend not only on the governance design, but on collective leadership and the ability to maintain shared action while navigating the road ahead. “Our advice remains the same as prior to this latest government announcement. That is to keep statutory service delivery moving and focus on decisions that will be unaffected by reorganisation. This means procuring through compliant, flexible routes that transfer cleanly to whatever structure eventually emerges. Similarly, ensure contract, asset and supplier data is in order because that is the groundwork every future authority will need regardless of how new boundaries are formed. Finally, keep the relationships with your supply chain warm so that you can move quickly when clarity comes. “Uncertainty is not the same as standstill. The authorities that come through this best will be the ones that use the pause to get their house in order – rather than waiting to be told what shape they’ll be.” For more information and guidance, check out Navigating Local Government Reorganisation – which was recently published by Pagabo. Building, Design & Construction Magazine | The Choice of Industry Professionals
Cardo Group Builds £314m Maintenance Business as Acquisition Strategy Accelerates
Cardo Group has rapidly expanded its position in the UK building maintenance market, creating a business with full-year revenues of £314 million following a sustained programme of acquisitions and organic growth. The Cardiff-based group, which specialises in repairs, maintenance and improvement services for the social housing sector, reported statutory turnover of £239 million for the year to February 2026, representing a 65% increase. Growth was supported by seven acquisitions during the period alongside expansion across Cardo’s existing operations, as the business continues to build greater regional coverage and broaden the specialist services it can provide to housing clients. Operating profit more than doubled from £6 million to £14 million, with the operating margin increasing from 4.3% to 5.8%. However, the scale of the enlarged group is better reflected by full-year trading figures incorporating 12 months of revenue from the acquired businesses, which put turnover at £314 million and adjusted EBITDA at almost £32 million. Cardo’s acquisition programme has brought a diverse range of building maintenance capabilities into the group. Deals have included Breyer’s roofing division, energy specialist SERS operations in Scotland and Wales, CTS Projects, Scottish roofing contractor Faskin Group, passive fire protection specialist Gunfire and Trident Maintenance Services. Expansion has continued since the financial year-end. Welsh electrical maintenance specialist EFS Systems (UK) joined Cardo in May, followed in July by R Lewis & Co (UK) Holdings and subsidiary R Lewis & Co (UK), strengthening the group’s passive fire safety capabilities. In August, Cardo added Andover-based plumbing and heating specialist Correct Contract Services, further expanding its building services offering and geographical reach. The acquisition strategy has been accompanied by significant workforce growth. Average employee numbers increased from approximately 780 to 1,276, with much of the expansion concentrated within operational roles. Cardo’s balance sheet also reflects the pace of investment. Cash increased from £9.9 million to £15.1 million, while long-term creditors rose from £30.5 million to £81.6 million as acquisition financing was deployed to support the group’s expansion. The business is now looking to combine further strategic acquisitions with organic growth secured through long-term repairs and maintenance contracts. Its strategy is particularly focused on strengthening regional delivery capabilities across the social housing market while bringing together complementary services including roofing, electrical works, heating, energy efficiency and passive fire protection. Further consolidation is also planned within Scotland, where Heatcare Oil and Gas and Rodgers & Johnston are set to be integrated into Cardo Scotland. With a strong forward order book and growing pipeline of opportunities, Cardo is positioning the enlarged group for further expansion as investment in housing maintenance, building safety, energy efficiency and asset improvement continues across the UK. Building, Design & Construction Magazine | The Choice of Industry Professionals
£120bn Government FM Framework Sets Stage for Major Public Estate Contracts
Some of the UK’s biggest facilities management and building services contractors have secured positions on a new government framework valued at up to £120 billion, opening the door to a major pipeline of public estate work over the next eight years. The Government Commercial Agency framework, RM6378, is set to become a recommended procurement route for facilities management services across central government. It will also be available to local authorities, NHS organisations, police forces, fire and rescue services, education bodies and devolved administrations. Competition for the largest Total Facilities Management contracts has attracted many of the sector’s leading names. Eighteen businesses have been appointed to the highest-value lot, covering individual contracts worth more than £15 million annually. The successful firms include Amey, CBRE, Compass, Dalkia, Equans, G4S Facilities Management, ISS, JLL, Kier, Mitie, OCS, Robertson Facilities Management, Serco, Skanska, Sodexo, Vinci Facilities, Vivo Defence Services and Wates. For the construction and built environment industry, the framework also represents a substantial opportunity for contractors delivering hard FM, engineering, maintenance and asset management services across the public estate. Forty businesses have secured positions on the major Hard FM lot for contracts valued above £2 million per year. Among those appointed are Amey, BAM FM, CBRE, Dalkia, Equans, Galliford Try, Graham Asset Management, Kier, Mears, Mitie, NG Bailey, OCS, Robertson, Serco, Skanska, Vinci Facilities, Vivo and Wates. The framework has been structured to accommodate public sector estates and contracts of significantly different scales. Total FM is divided into three bands covering contracts worth up to £2 million annually, between £2 million and £15 million, and more than £15 million. Hard FM is split between contracts below and above £2 million a year. A core group of contractors has achieved particularly strong coverage across the framework. Fifteen firms secured places across all five Total FM and Hard FM lots: Amey, CBRE, Equans, ISS, JLL, Kier, Mitie, OCS, Robertson, Serco, Skanska, Sodexo, Vinci Facilities, Vivo Defence Services and Wates Property Services. A further group, including BAM FM, Dalkia Facilities, Galliford Try Facilities Management, Graham Asset Management and Mears FM, secured positions across four lots. The scale and duration of the framework make it an important development for the management and maintenance of the UK’s public buildings and infrastructure. Alongside day-to-day FM provision, major hard services contracts can encompass the engineering, maintenance and long-term performance of complex property portfolios. With public bodies continuing to face pressure to improve building efficiency, modernise ageing estates and manage assets more effectively, the framework provides a long-term procurement platform through which significant programmes of FM and building services work can be commissioned. The agreement is scheduled to operate for eight years, running through to August 2034, giving successful contractors access to what could become one of the most significant public sector facilities management pipelines in the UK. Main Total FM and Hard FM winners Building, Design & Construction Magazine | The Choice of Industry Professionals
SmartBarrel Listicle Addition
Row for “Best GPS Time Clock Apps for Construction Crews in the US at a Glance” table App GPS Method Geofencing Offline Scheduling Payroll Sync Job Costing Kiosk From $ Trial SmartBarrel Geofenced clock-in + biometric facial verification (LTE hardware + mobile apps) ✅ ✅ Built-in LTE ❌ ✅ ✅ ✅ Custom pricing Demo #[X] SmartBarrel: Best for Verifying On-Site Hours Across Large Specialty Contractor Crews SmartBarrel is a construction time clock that pairs geofencing with biometric facial verification, giving contractors a way to confirm that each worker on the timecard was physically on the jobsite at clock-in and clock-out. It’s built for specialty contractors and self-perform general contractors tracking their own crews, typically on jobsites with 10 or more workers. Most GPS time clocks confirm where a phone or kiosk was when a punch happened. That answers the location question, but on large crews a location check alone doesn’t confirm that every worker listed was present. SmartBarrel adds a second check: each clock-in photo is compared against that worker’s previous check-ins, and anything that looks off gets flagged on the dashboard for review. The TimeClock 4.0 device mounts magnetically, runs on electricity, solar, or Milwaukee and DeWalt battery packs, and connects over built-in LTE, so time data reaches the dashboard in real time without relying on jobsite Wi-Fi. For smaller or mobile crews, the Kiosk App and Personal App add geofencing, where a project only appears when the worker is physically on site. SmartBarrel positions the combination around delivering the most accurate time from the field. What are SmartBarrel’s key features? How much does SmartBarrel cost? What are the pros and cons of SmartBarrel? Pros: Cons: What are the use cases of SmartBarrel? SmartBarrel fits specialty contractors in electrical, concrete, MEP, drywall, solar, and glass and glazing who run large crews across multiple jobsites. It’s especially useful on T&M projects where contractors need time records that hold up to GC or owner review, and on jobs that mix direct employees, temp labor, and union hires.
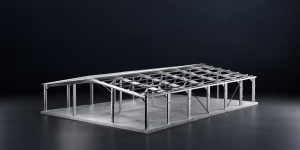
Schedule, stamped drawings and expansion: why low-rise developers keep choosing pre-engineered steel
Pre-engineered steel is taking share in low-rise commercial development because it moves structural engineering, fabrication and quality control off the site and into a factory, which shortens the critical path and puts a code-ready, stamped drawing set in the developer’s hands earlier than conventional construction usually manages. Metal building systems account for a substantial share of new low-rise, nonresidential floor area in the United States, a position the Metal Building Manufacturers Association follows through its industry trends reporting, and that share was built up over decades on warehouses, light industrial units, retail shells, offices and mixed-use blocks of two or three storeys. The model is less familiar to UK developers, but the reasoning behind it travels, and so does the main procurement trap inside it. Most published comparisons of pre-engineered steel lead with cost. That framing is the least useful one for a developer, because price is the output of a specification that has not been written yet. The four things worth examining before that point are schedule sequencing, the engineering documents, how expansion gets designed in, and who you are actually buying from. The schedule argument is a sequencing argument The schedule gain in a pre-engineered steel building comes from parallel work, not from fast erection. While the primary frames, secondary framing and cladding are being fabricated in a plant, the site is doing groundworks, drainage and foundations, so two long-lead activities run side by side instead of end to end. Erection is quick once the steel lands, but erection was never the part of the programme that hurt. That parallel sequence only holds if the design is frozen early. A pre-engineered system prices and fabricates against a fixed geometry, load case and opening schedule, so a decision to move a roller door or add a mezzanine after release to fabrication costs far more programme time than the same change would in a steel-frame build detailed on site. Developers who do well out of the format tend to be the ones who run their tenant conversations before release, not after. Weather exposure is the other schedule variable that changes shape. Factory fabrication in controlled conditions removes a large block of field labour from the programme, which matters more in a wet winter than any theoretical erection rate does. The site crew is bolting together finished members rather than cutting, fitting and welding in the open. Stamped drawings are the part developers underestimate Engineering documentation is the quiet reason pre-engineered systems clear approvals faster. A genuine manufacturer produces the anchor bolt plan, reactions, frame cross-sections and erection drawings as part of the order, sealed by a professional engineer licensed in the project’s jurisdiction, so the building official and the developer’s own structural consultant are reviewing a coordinated set rather than assembling one. The practical value shows up at two moments. The first is permitting, where a complete stamped package tends to attract fewer requests for information. The second is foundation design, because the manufacturer’s reaction data is what the geotechnical and foundation engineers need before anyone pours anything, and late reactions stall the site while the steel sits in a plant yard. Ask at tender stage when the stamped drawings arrive, who seals them, and whether design changes after approval trigger a re-seal. The answers differentiate suppliers more sharply than any brochure claim about steel grade. Expansion has to be engineered before the first bolt goes in Expansion in a pre-engineered steel building is cheap if it was planned and awkward if it was not. A frame ordered as expandable gets a rigid endwall rather than a bearing endwall, with the foundations, bracing and reactions sized for the future bays, so adding 60 or 80 feet later means unbolting the sheeting and continuing the line. A frame ordered without that provision needs the endwall rebuilt and the foundations reworked, which is a different project. Developers holding land for phased delivery, or letting to tenants with growth clauses, should specify the expansion case in the original enquiry even if they never use it. The design cost of an expandable endwall is modest at order stage and effectively unrecoverable afterwards. Bolted steel frames also come apart, which matters for exit strategy and for planning arguments about circularity. UK guidance on recycling and reuse of structural steel records recovery rates for structural sections at the top end of construction materials, and a bolted, documented frame is considerably easier to demount and reuse than a welded or composite one. Manufacturer or broker is the question that decides the rest Much of the pre-engineered steel market is sold by brokers, dealers and kit resellers who do not own a plant, do not employ engineers and pass the order to whichever fabricator quotes best that month. The distinction is invisible in marketing and very visible in a dispute, because a reseller cannot reseal a drawing, cannot reschedule a fabrication slot and cannot answer a technical query without relaying it. Developers who buy on schedule certainty should be establishing, in writing, whether the counterparty manufactures. Buying manufacturer-direct compresses the chain to one accountable party for engineering, fabrication and delivery. Universal Steel of America, a Peachtree Corners company founded in 1995 that manufactures pre-engineered systems for low-rise projects only, runs that model across its commercial steel buildings work, with in-house engineering, PE-stamped drawings, and a stated plant network covering every region of the United States that ships directly to site from the closest plant. The point for a developer is not the brand but the structure of the relationship: when the engineer, the fabricator and the shipper answer to the same company, a mid-project change has one owner rather than three. Third-party accreditation helps test the claim. IAS AC472 accredits a metal building manufacturer’s design, fabrication and inspection programme, and a building official may accept that accreditation as evidence that the manufacturer qualifies as an approved fabricator under Chapter 17 of the International Building Code, which can remove duplicate in-shop inspections. One detail gets misread often: AC472