Business : BDC Insight News
MILWAUKEE® reveals the true cost of petrol on urban construction sites

MILWAUKEE® reveals the true cost of petrol on urban construction sites

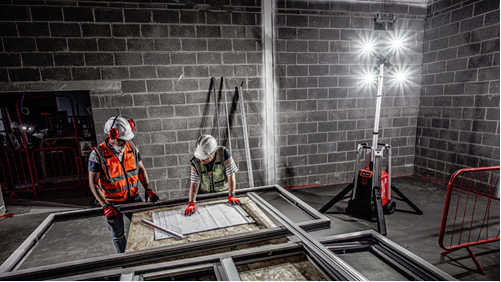
MILWAUKEE® Tools new ‘Room to Breathe’ whitepaper for MX FUEL™ sets out the environmental, health and financial case for replacing petrol-powered light equipment with MX FUEL™ battery-powered alternatives across EMEA: Petrol-powered equipment is a significant and overlooked source of air pollution, health risk and compliance liability on construction sites. New

Read More »
Schedule, stamped drawings and expansion: why low-rise developers keep choosing pre-engineered steel

Schedule, stamped drawings and expansion: why low-rise developers keep choosing pre-engineered steel

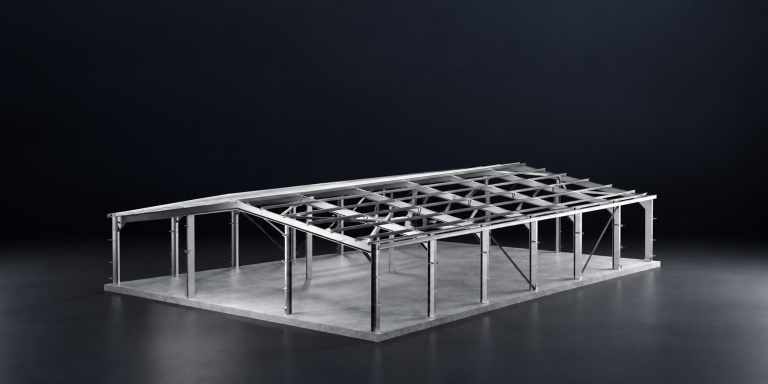
Pre-engineered steel is taking share in low-rise commercial development because it moves structural engineering, fabrication and quality control off the site and into a factory, which shortens the critical path and puts a code-ready, stamped drawing set in the developer’s hands earlier than conventional construction usually manages. Metal building systems

Read More »
Why hotels and hospitality venues present unique maintenance challenges and how FM teams can overcome them

Why hotels and hospitality venues present unique maintenance challenges and how FM teams can overcome them

From budget hotel chains to luxury resorts and large restaurant groups, hospitality venues face some of the most complex operating environments, regulatory obligations, and maintenance requirements.  These properties contain a wide variety of spaces, building systems and assets, from bedrooms and event spaces to commercial kitchens, HVAC and water systems,

Read More »
Confidence gap: 70% of architects say they meet acoustic needs, but sound is rarely considered before Stage 4

Confidence gap: 70% of architects say they meet acoustic needs, but sound is rarely considered before Stage 4

New research from Oscar Acoustics has revealed a disconnect between industry confidence in meeting people’s acoustic needs and the point at which acoustics are actually considered in the design and construction process. Seven in ten (70.4%) UK architects and construction professionals say they are confident they meet the acoustic requirements

Read More »
Modular Technology: Hidden in Plain Sight

Modular Technology: Hidden in Plain Sight

The next time you buy a coffee, check into a hotel, visit a healthcare facility, stop at a motorway service area or walk into a modern workplace or school, take a moment to look around. Richard Hipkiss, development director, Modular and Portable Building Association (MPBA) considers the buildings you use

Read More »
Government procurement simplification welcomed by Pagabo Group CEO

Government procurement simplification welcomed by Pagabo Group CEO

By Amman Boughan, CEO at Pagabo Group. Members of the new Labour cabinet are busy making their arrival known, with announcements coming thick and fast. Procurement has been a frequent talking point for prime minister Andy Burnham since his resurgence and rise to the top of government. However, talking is

Read More »
7 Exciting Trends in Communal Area Design

7 Exciting Trends in Communal Area Design

Communal areas have become one of the most closely watched categories in commercial design. As organizations rethink how much space they need and what that space should do, shared lounges, break rooms and collaboration zones are being asked to work harder than ever. You’re no longer just planning a lunchroom

Read More »
What Goes Into Efficient Waste Management? Insights, Programs and More

What Goes Into Efficient Waste Management? Insights, Programs and More

The sheer volume of waste the construction industry generates raises critical questions about efficient management practices. In response, building design and construction professionals are shifting away from reactive disposal toward digital waste management solutions that protect profit margins while improving operational efficiency. As companies evaluate how different waste management software

Read More »
Latest Issue
Issue 345 : Oct 2026

Business : BDC Insight News

UK logistics market demand remains resilient amid sharp slowdown in new development

UK logistics market demand remains resilient amid sharp slowdown in new development

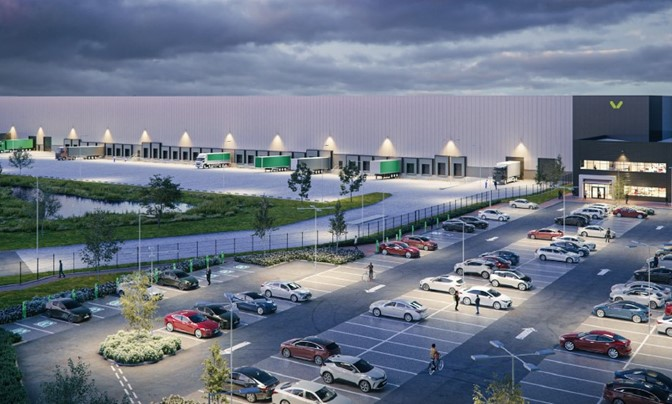
Constrained pipeline expected to support rental growth The UK industrial and logistics market continued to demonstrate resilience during Q3 2026, with occupier demand remaining ahead of long-term averages despite ongoing economic uncertainty and extended decision-making timelines. According to Colliers’ latest data, take-up of units over 100,000 sq ft reached 6.7 million sq ft during Q3, taking year-to-date (YTD) volumes to 21.8 million sq ft, slightly ahead of the pre-pandemic 10-year average. Activity remains concentrated among a core group of occupiers and locations and continues to be driven by retail, e-commerce and fulfilment businesses, which collectively account for 78% of YTD take-up. The Midlands remains the dominant logistics market, accounting for 63% of all space transacted so far this year. Several major deals completed during the quarter, including Super Smart Service expanding its Midlands footprint through a number of 15-year lease commitments, DIRKS Consumer Logistics pre-letting 306,000 sq ft at SEGRO Park Coventry, DHL pre-letting 450,000 sq ft at Westworks Corby, and TikTok committing to the recently completed Rugby 251 for its ecommerce platform. However, the defining trend in the market continues to be on the supply side, where development activity has fallen sharply. Although availability edged up slightly during the quarter, the UK vacancy rate held steady at 8.6%. Crucially, the quarterly increase has not been driven by new speculative development. Q3 speculative completions totalled less than 500,000 sq ft, marking the lowest quarterly delivery volume in nearly 10 years. Over the past 12 months, the amount of newly built space available across the UK has fallen by 10.3%, while second-hand availability has increased by 20%. New Grade A stock now accounts for just 36% of available space, down from 43% a year ago. Looking ahead, only 7.3 million sq ft of speculative space is currently expected to complete in 2026, representing a 45% shortfall against the five-year average, and the lowest annual delivery volume since 2018. Deirdre O’Reilly, Head of Industrial Research UK at Colliers, said: “The UK logistics occupier market continues to prove more resilient than the wider economic backdrop might suggest. While occupiers are taking a little longer to press the button, demand remains healthy and is well on track to deliver take-up of around 30 million sq ft this year. “Development activity has slowed considerably, resulting in a shrinking pipeline of new Grade A logistics space coming forward. Although vacancy has risen modestly again, the proportion of new and modern space available is falling, which means occupiers are facing a more competitive environment for the highest-quality space in the right locations.” The slowdown in development reflects a trend being seen across Europe, where industrial and logistics space under construction has declined significantly over the past year. At the same time, vacancy rates across many European markets are beginning to stabilise, supporting a more balanced outlook for the sector. Average rental growth remains positive across the UK, with rents increasing by 4.3% year-on-year in August, while prime big-box rents rose 2.7% annually to September. However, net effective rental growth continues to be moderated by increasing incentive packages, with average rent-free periods rising from 14.8 months last year to 15.8 months in 2026. Len Rosso, Co-Head of Industrial & Logistics at Colliers, added: “Retailers, e-commerce businesses and fulfilment operators continue to drive demand across the logistics sector, with Chinese occupiers remaining a particularly important source of activity. These businesses remain focused on core Golden Triangle locations that offer access to the majority of the UK’s consumer population. “With around 15 million sq ft currently under offer and the development pipeline becoming increasingly constrained, well-located logistics assets should remain well-positioned, not only supporting landlord confidence but reinforcing the importance of early decision-making for occupiers. The availability of new, high-quality space is becoming more and more limited, and that is likely to support rental growth prospects in the coming year.” Building, Design & Construction Magazine | The Choice of Industry Professionals

Read More »
MILWAUKEE® reveals the true cost of petrol on urban construction sites

MILWAUKEE® reveals the true cost of petrol on urban construction sites

MILWAUKEE® Tools new ‘Room to Breathe’ whitepaper for MX FUEL™ sets out the environmental, health and financial case for replacing petrol-powered light equipment with MX FUEL™ battery-powered alternatives across EMEA: Petrol-powered equipment is a significant and overlooked source of air pollution, health risk and compliance liability on construction sites. New MILWAUKEE® research across more than 2,000 professional users in EMEA makes the case for accelerating the transition to battery power. The hidden cost of petrol on the construction site Petrol-powered equipment contributes to more than 108 million tonnes of CO₂ annually, with air pollution costing the EU around €600 billion a year, equivalent to 4% of GDP. WHO Europe and the European Respiratory Society report that respiratory diseases account for more than €17 billion in annual productivity losses. The human cost One in three construction workers is exposed to harmful fumes three to five days per week. On urban sites, petrol-powered tools also release harmful PM2.5 particulate matter and nitrogen dioxide (NO₂). Prolonged exposure to harmful fumes is linked to asthma, COPD, lung cancer and cardiovascular disease. The shift to battery Three in four respondents to MILWAUKEE®’s survey rate their cordless experience as good or excellent. Four in five believe battery systems can serve as true petrol replacements, with noise reduction (31.8%), environmental benefits (21%) and health improvements (16%) cited as the primary motivations. As the ‘Room to Breathe’ whitepaper reveals, on total cost of ownership, the numbers make a strong case for battery power adoption. The MX FUEL™ Cut-Off Saw delivers more than €240 in annual savings over its petrol equivalent; the Breaker saves around €1,700 per year; the Tower Light saves approximately €1,800 per year. Battery equipment also eliminates recurring costs for spark plugs, filters, carburettors, air filters, drive belts and starter cords. Real-world proof Skanska Rental in Sweden ran a two-year trial before committing to full MX FUEL™ adoption. Mirza Palislamovic, Product Manager at Skanska Rental, Sweden, said safety was central to the decision. “For Skanska, safety is number one and always has been. So, if we have a product with better safety features like MX FUEL™’s AUTOSTOP™ feature, then of course it’s a big plus.” The direction of travel is clear. Palislamovic added, “By 2027, we will have all battery machines instead of petrol. So, I don’t see any problems in going from petrol to battery power.” The path forward California has banned new petrol-powered tools in built-up areas. More than 100 US municipalities have enacted restrictions, and Stockholm and Oslo have established no-emission zones. European regulators are watching closely. The ‘Room to Breathe’ whitepaper outlines the priorities the industry should champion: supporting the expansion of civic no-emission zones, educating end users on the full benefits of battery power, investing in charging infrastructure and demonstrating battery performance in real working conditions. MILWAUKEE® Jobsite Solutions (JSS) team are available to work directly with end-users, providing hands-on demonstrations across the MX FUEL™ range to help teams understand performance, runtime and total cost of ownership in the context of their own operations. To download the Room to Breathe (MX FUEL™ edition) whitepaper, click here. To find out more about MILWAUKEE®, click here. Building, Design & Construction Magazine | The Choice of Industry Professionals

Read More »
Schedule, stamped drawings and expansion: why low-rise developers keep choosing pre-engineered steel

Schedule, stamped drawings and expansion: why low-rise developers keep choosing pre-engineered steel

Pre-engineered steel is taking share in low-rise commercial development because it moves structural engineering, fabrication and quality control off the site and into a factory, which shortens the critical path and puts a code-ready, stamped drawing set in the developer’s hands earlier than conventional construction usually manages. Metal building systems account for a substantial share of new low-rise, nonresidential floor area in the United States, a position the Metal Building Manufacturers Association follows through its industry trends reporting, and that share was built up over decades on warehouses, light industrial units, retail shells, offices and mixed-use blocks of two or three storeys. The model is less familiar to UK developers, but the reasoning behind it travels, and so does the main procurement trap inside it. Most published comparisons of pre-engineered steel lead with cost. That framing is the least useful one for a developer, because price is the output of a specification that has not been written yet. The four things worth examining before that point are schedule sequencing, the engineering documents, how expansion gets designed in, and who you are actually buying from. The schedule argument is a sequencing argument The schedule gain in a pre-engineered steel building comes from parallel work, not from fast erection. While the primary frames, secondary framing and cladding are being fabricated in a plant, the site is doing groundworks, drainage and foundations, so two long-lead activities run side by side instead of end to end. Erection is quick once the steel lands, but erection was never the part of the programme that hurt. That parallel sequence only holds if the design is frozen early. A pre-engineered system prices and fabricates against a fixed geometry, load case and opening schedule, so a decision to move a roller door or add a mezzanine after release to fabrication costs far more programme time than the same change would in a steel-frame build detailed on site. Developers who do well out of the format tend to be the ones who run their tenant conversations before release, not after. Weather exposure is the other schedule variable that changes shape. Factory fabrication in controlled conditions removes a large block of field labour from the programme, which matters more in a wet winter than any theoretical erection rate does. The site crew is bolting together finished members rather than cutting, fitting and welding in the open. Stamped drawings are the part developers underestimate Engineering documentation is the quiet reason pre-engineered systems clear approvals faster. A genuine manufacturer produces the anchor bolt plan, reactions, frame cross-sections and erection drawings as part of the order, sealed by a professional engineer licensed in the project’s jurisdiction, so the building official and the developer’s own structural consultant are reviewing a coordinated set rather than assembling one. The practical value shows up at two moments. The first is permitting, where a complete stamped package tends to attract fewer requests for information. The second is foundation design, because the manufacturer’s reaction data is what the geotechnical and foundation engineers need before anyone pours anything, and late reactions stall the site while the steel sits in a plant yard. Ask at tender stage when the stamped drawings arrive, who seals them, and whether design changes after approval trigger a re-seal. The answers differentiate suppliers more sharply than any brochure claim about steel grade. Expansion has to be engineered before the first bolt goes in Expansion in a pre-engineered steel building is cheap if it was planned and awkward if it was not. A frame ordered as expandable gets a rigid endwall rather than a bearing endwall, with the foundations, bracing and reactions sized for the future bays, so adding 60 or 80 feet later means unbolting the sheeting and continuing the line. A frame ordered without that provision needs the endwall rebuilt and the foundations reworked, which is a different project. Developers holding land for phased delivery, or letting to tenants with growth clauses, should specify the expansion case in the original enquiry even if they never use it. The design cost of an expandable endwall is modest at order stage and effectively unrecoverable afterwards. Bolted steel frames also come apart, which matters for exit strategy and for planning arguments about circularity. UK guidance on recycling and reuse of structural steel records recovery rates for structural sections at the top end of construction materials, and a bolted, documented frame is considerably easier to demount and reuse than a welded or composite one. Manufacturer or broker is the question that decides the rest Much of the pre-engineered steel market is sold by brokers, dealers and kit resellers who do not own a plant, do not employ engineers and pass the order to whichever fabricator quotes best that month. The distinction is invisible in marketing and very visible in a dispute, because a reseller cannot reseal a drawing, cannot reschedule a fabrication slot and cannot answer a technical query without relaying it. Developers who buy on schedule certainty should be establishing, in writing, whether the counterparty manufactures. Buying manufacturer-direct compresses the chain to one accountable party for engineering, fabrication and delivery. Universal Steel of America, a Peachtree Corners company founded in 1995 that manufactures pre-engineered systems for low-rise projects only, runs that model across its commercial steel buildings work, with in-house engineering, PE-stamped drawings, and a stated plant network covering every region of the United States that ships directly to site from the closest plant. The point for a developer is not the brand but the structure of the relationship: when the engineer, the fabricator and the shipper answer to the same company, a mid-project change has one owner rather than three. Third-party accreditation helps test the claim. IAS AC472 accredits a metal building manufacturer’s design, fabrication and inspection programme, and a building official may accept that accreditation as evidence that the manufacturer qualifies as an approved fabricator under Chapter 17 of the International Building Code, which can remove duplicate in-shop inspections. One detail gets misread often: AC472

Read More »
Why hotels and hospitality venues present unique maintenance challenges and how FM teams can overcome them

Why hotels and hospitality venues present unique maintenance challenges and how FM teams can overcome them

From budget hotel chains to luxury resorts and large restaurant groups, hospitality venues face some of the most complex operating environments, regulatory obligations, and maintenance requirements.  These properties contain a wide variety of spaces, building systems and assets, from bedrooms and event spaces to commercial kitchens, HVAC and water systems, lifts and leisure facilities.  Maintenance is therefore critical not only to compliance and long-term asset value but also to guest satisfaction and brand reputation, meaning there is little room for disruption or error, especially during periods of peak occupancy.   Matt Voyle, Senior Account Executive at SFG20, the industry standard for hotel facilities management, has shared the key challenges facing hotels and hospitality venues today and why a structured approach to planned maintenance is essential for FM teams operating across the sector. A significant water-safety risk in hotels and hospitality venues is Legionella. When guest rooms, outlets, or sections of a water system are used infrequently, water can stagnate and create conditions favourable to bacterial growth. Seasonal properties and temporarily closed wings therefore require particular attention.  Control should be based on a suitable risk assessment and managed by someone with the appropriate knowledge and training. Depending on the systems and the findings of the assessment, measures may include temperature control, regular flushing of infrequently used outlets, inspection, cleaning and descaling, and documented checks. FM teams can strengthen control by maintaining reliable information about their water systems and implementing a risk-assessment-led maintenance regime. Appropriate monitoring technology may support this approach, but it does not replace the required assessment, controls, and documented checks.  Unlike offices or retail environments, where lower-occupancy periods allow planned maintenance to take place with minimal disruption, hotel and hospitality venues have to accommodate guests day and night.  Hotels, as well as cafes and restaurants, have very small downtime windows, giving little time for anything other than routine checks. This means small issues can go unnoticed, potentially developing into larger problems further down the line.  Maintenance planning must therefore avoid a one-size-fits-all approach and instead be precise and structured around the operational realities of each property rather than being generically applied across the estate.  The condition and performance of hotel and hospitality buildings is highly visible to guests, meaning there’s zero room for failure. Issues with HVAC, hot water, lifts, lighting, plumbing or other facilities can quickly lead to complaints, negative reviews and lost return business. Common issues include water temperature problems, noise complaints, humidity, kitchen extract failures, false fire alarms and out-of-service lifts, which can all impact accessibility and guest satisfaction. For hotel management companies overseeing maintenance across multiple properties, consistent FM performance is essential for meeting brand standards, supporting owner and operator reporting and protecting the long-term value of assets. Large hotel and hospitality operators often manage estates spanning properties of different ages, formats, historic importance and building types, each with their own asset profiles and maintenance histories. This creates additional complexity for FM teams, particularly when managing heritage properties that may be subject to planning or conservation constraints alongside independently branded and franchised sites with different standards and owner expectations. Without a common maintenance baseline, standards can vary and compliance gaps can emerge, while inconsistencies become increasingly costly to resolve as portfolios grow. Holiday parks and resorts present a particularly complex FM environment, combining different accommodation types such as lodges, holiday homes, cottages, and apartments with commercial kitchens, dining areas, pools, gyms, entertainment facilities, and outdoor amenities. The diversity of these building types, as well as asset ages and infrastructure, combined with seasonal demand, makes it difficult for FM teams to apply a generic maintenance approach. This becomes even more complex when it comes to all-inclusive resorts, where guests have limited alternatives to facilities on site.  Matt Voyle adds:  “With maintenance varying from property to property, having a trusted framework for planned maintenance, organisations and venues can create a more consistent and structured approach. For hotels and hospitality organisations, that means identifying applicable maintenance tasks and recommended frequencies, distinguishing statutory requirements from industry best practice, and documenting where site-specific tailoring is needed. Hospitality estates vary widely. A strong approach combines a consistent baseline with controlled, evidence-based tailoring, creating a maintenance regime that is practical, auditable and commercially workable Download SFG20’s free e-guide, How Hotels and Hospitality FM Teams Can Improve Compliance, Control Costs and Run More Efficiently, for practical guidance on reviewing and strengthening your maintenance approach.” Building, Design & Construction Magazine | The Choice of Industry Professionals
Read More »
Confidence gap: 70% of architects say they meet acoustic needs, but sound is rarely considered before Stage 4

Confidence gap: 70% of architects say they meet acoustic needs, but sound is rarely considered before Stage 4

New research from Oscar Acoustics has revealed a disconnect between industry confidence in meeting people’s acoustic needs and the point at which acoustics are actually considered in the design and construction process. Seven in ten (70.4%) UK architects and construction professionals say they are confident they meet the acoustic requirements of everyone who uses a building, including neurodivergent people and those with hearing challenges. Yet the research suggests acoustics are often not given proper consideration until key decisions affecting how a space will sound have already been made. Acoustics comes too late in the process The research, commissioned by Oscar Acoustics and conducted among 500 UK construction professionals and 250 UK architects, shows how late acoustics can enter the process. Among architects, nearly six in ten (57.2%) say acoustics do not get proper attention until RIBA Stage 4, Technical Design, or Stage 5, Construction.By this point, decisions around layout and materials are largely settled, limiting the opportunity to design for sound from the outset and making problems harder to address later. Construction professionals describe a similar pattern. Fewer than one in 25 (3.6%) say acoustics is considered at the initial client briefing stage, when there is still an opportunity to shape the fundamentals of a scheme. Meanwhile, around a third (33.8%) leave it until construction or fit-out, once the building’s shell is already up. The consequences of getting acoustics wrong Poor acoustic environments are estimated to cost UK businesses more than £40 billion a year* through lost productivity, staff turnover and customer dissatisfaction. The impact is also felt by the people using these spaces. When acoustics are addressed late in the process, the needs and experiences of occupants risk being considered after many of the critical decisions affecting their environment have already been made. Designing for people, not averages Gillian Burgis Smith, founder of inclusive design consultancy Strawberry Leopard Limited and co-creator of the “Joyful Journey” methodology, has experienced this disconnect first hand. Following two strokes and a brain tumour diagnosis in 2019, her own experience of the built environment changed profoundly, highlighting why environments must be shaped by lived and living experience, not assumptions about an “average” user. She said: “The disconnect comes from confidence being mistaken for competence at implementation and that is where the gap opens up.” “The profession is becoming more confident about the language of neuro-inclusive and sensory design, but less consistent in the systems needed to deliver it. You have to bring in people with lived and living experience, and design must adapt to the needs of the user, not the other way around. “In practice, that means testing designs with diverse users early and often, then iterating so spaces work for real people, not averages. A building is a dynamic ecosystem for a dynamic ecosystem of people.” Where confidence and practice diverge Ben Hancock, Managing Director of Oscar Acoustics, said: “While architects and construction professionals feel confident about meeting people’s acoustic needs, our research suggests there is a gap between that confidence and the point at which acoustics are considered in practice.” “When acoustic design is considered as a late-stage addition, rather than a core element of the building strategy, it can have a severe impact on the people who use a space. “This is particularly the case for the 60% of UK adults who are noise-sensitive, including neurodivergent individuals and those with hearing challenges. “But poor acoustics also cost businesses directly, through lower productivity, higher staff turnover and reduced office attendance. The industry is taking a risk not only with people’s wellbeing but also with its own clients’ bottom line.” Calls for greater industry support The findings also suggest architects and construction professionals want more formal support around acoustic design. Around one in six (15.8%) construction professionals and one in five (19.2%) architects back a recognised certification for acoustically inclusive buildings. Meanwhile, around one in five (19.4%) construction professionals and more than one in five (22.0%) architects want mandatory acoustic standards written into building regulations. A framework for acoustic inclusion Sownd Certification, developed by Sownd Affects, with independent testing carried out by the Institute of Sound and Vibration Research at the University of Southampton, is the world’s first framework recognising spaces with proven acoustic performance as audio-inclusive. It assesses spaces across three tiers, from Bronze foundations through to Silver and Gold, based on measures including reverberation time, background noise and speech clarity. Oscar Acoustics’ Innovation Centre in Halling, Kent, is the world’s first Sownd Certified building, providing architects and specifiers with a working example of acoustically inclusive design in practice. To find out more about Sownd Certification or to arrange a visit to Oscar Acoustics’ Innovation Centre in Halling, Kent, visit https://www.oscar-acoustics.com/. Building, Design & Construction Magazine | The Choice of Industry Professionals
Read More »
The Evolution of Safe Construction: Working Without 'Hot Works' Permits

The Evolution of Safe Construction: Working Without ‘Hot Works’ Permits

Every time a torch lights on a British site, paperwork starts. A Hot Work Permit, a safety briefing, a marked-out zone, and at least an hour of continuous fire watch after the work stops. None of this is box-ticking: insurance cover for most large contractors is tied directly to compliance. The trade has spent the last decade moving away from open flame wherever it can, and press-fit technology is one of the clearest drivers of the shift. Understanding ‘Hot Works’ and Their Inherent Risks Hot work covers any task that involves open flame, heat or sparks. Welding, cutting, soldering, grinding and torch-applied roofing all fall under that heading. On site, any such activity normally needs a Hot Work Permit. It’s issued by an authorised person before the shift begins and sets out the location, the cleared zone, the extinguishers on hand and the named fire watch. The regulatory backdrop has several layers. HSE’s HSG168 (third edition) expects designers to consider flameless alternatives at the planning stage, alongside CDM 2015. The Joint Code of Practice (JCoP, tenth edition), drawn up by the FPA and RISCAuthority with insurer backing, applies to projects valued at £2.5m and up. It requires at least an hour of continuous fire watch after work stops, with checks every twenty minutes for the next hour and up to three hours on higher-risk jobs. The numbers explain the strictness. CE Safety, drawing on ONS data, recorded 381 hot-work fires in England across 2023/24 and 2024/25, with welding and cutting accounting for 85%. The most damaging recent case struck Selsey Academy in West Sussex in 2016: losses near £20m, ignition traced to a gas torch during roof repairs. Figures like these underpin the case for flame-free systems such as press fit fittings, where joints go together without a torch or a permit. The Industry Shift Toward Flameless Construction Technologies HSG168 puts it plainly: design hot work out wherever you can. If you can’t, look at flameless alternatives first. NFRC carries the same principle into roofing through its Safe2Torch initiative. The reasoning is practical. Every job done without an open flame saves a permit, a fire watch, an insurance exposure and downtime on site. Flameless covers a family of methods, not one technology: For internal plumbing and heating, press-fit is now the de facto standard on commercial sites and is spreading fast into residential work. How Press Fit Fittings Revolutionised Pipe Installations The story begins in 1963. Swedish engineer Gunnar Larsson introduced the first range of pressfittings for copper, steel and stainless tubing, alongside the hydraulic press tool. Mannesmann AG ran the system until 2004 when the business passed to Geberit. The contour seal, brought in around the turn of the millennium, was the turning point. It took press-fit into the mainstream British market and bedded it into the trade. Large commercial contractors took it up first, but the picture has shifted sharply over the last ten to fifteen years. Sole traders and small crews are investing in press tools because the payback on two or three big jobs is obvious. Today’s choice is broad: Geberit Mapress, Viega Profipress, Conex B Press, alongside M-Profile own-label ranges from UK distributors. Sourcing for a specific job (potable water, gas, heating) goes through specialist trade suppliers, and on most tasks M-Profile covers the full 15mm to 108mm range. Time and Cost Efficiency in Modern Projects Speed comes up first in nearly every conversation. Manufacturers and trade publications cite 50 to 80% time savings against soldered joints. Viega quotes a single connection in “under twenty seconds” and an 80% cut in installation time across a full system. On site the gap is often wider. On the Trade Legends podcast, Rothenberger UK’s spokesperson described jobs that used to take two or three days wrapping up in three hours. Speed isn’t the only saving. A pressed joint takes pressure immediately, with no cooling-down period eating minutes off every connection. Consumables drop out too: flux, solder, cleaner and tape are no longer needed. Assemblies can be prefabricated on or off site, and pressure tests can run with water already in the lines, which suits retrofit work. The biggest operational shift comes back to fire safety. No open flame, no permit, no fire watch, no breach of insurance terms, no stoppages while a fire officer inspects the job. The evolution of safer construction comes down to more than one technology. But the move from soldering to pressing is one of its clearest chapters. Less paperwork, less risk, more output per shift.

Read More »
Modular Technology: Hidden in Plain Sight

Modular Technology: Hidden in Plain Sight

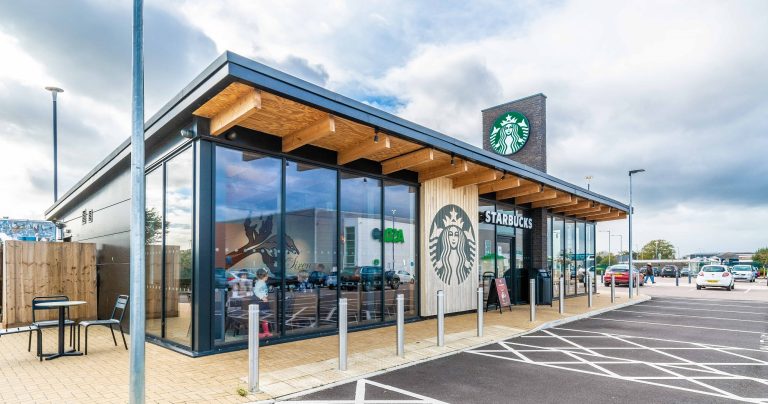
The next time you buy a coffee, check into a hotel, visit a healthcare facility, stop at a motorway service area or walk into a modern workplace or school, take a moment to look around. Richard Hipkiss, development director, Modular and Portable Building Association (MPBA) considers the buildings you use every day — but never knew were modular. Part of everyday life There is a very real possibility that you are standing inside a modular building – but you probably would not know it and that is exactly the point. For decades, modular construction has been fighting against outdated perceptions. The term ‘modular’ has been associated with temporary structures, classrooms or buildings that are visibly different from traditionally constructed properties. But that image belongs firmly in the past. Today, our modular manufacturing members are producing high-quality, permanent buildings that are designed, produced and finished to the highest standards. The reality is that modular buildings are already part of everyday life. They are occupied by thousands of people, yet most customers, visitors and end users have no idea that they were created in a factory environment. Across the UK, volumetric modular solutions have been adopted across a wide range of sectors, including retail, hospitality, healthcare, education and commercial developments. Some of the country’s best-known brands have embraced modular technology because it enables them to deliver consistent, high-quality facilities – quickly and efficiently. Retail businesses, for example McDonalds and Starbucks – need environments that reflect their brand identity while also meeting tight programme schedules. Whether it is a coffee shop, a restaurant unit, a hotel bedroom or a customer-facing facility, volumetric construction provides the ability to manufacture repeatable, precision-engineered buildings that can be installed rapidly with minimal disruption. The customer sees the finished result. They experience the service, the quality and the surroundings. They rarely consider the factory where much of the building was created. This is one of the biggest strengths of modern modular construction. Proven solution Unlike traditional construction, where many activities are carried out sequentially on a live site, modular manufacturing allows multiple processes to happen at the same time. While foundations are being prepared on site, building modules can be manufactured, fitted out and quality checked in a controlled factory environment. The result is greater certainty around programme delivery, improved quality control and reduced disruption. For sectors such as healthcare and education, where time and reliability are critical, these advantages are particularly valuable. Hospitals need additional capacity delivered quickly. Schools need new facilities that can be provided around operational requirements. Businesses need buildings that allow them to grow without lengthy construction programmes. Modular technology provides a proven solution to these challenges. Quality controlled The growing adoption of modular technology also reflects a wider shift towards more sustainable ways of building. Factory-based manufacturing allows materials to be managed more efficiently, waste to be reduced and quality to be controlled throughout the process. The modular sector does not necessarily need to prove that its buildings work. The evidence is already all around us. The challenge is helping people recognise that the buildings they interact with every day may have been delivered through advanced offsite manufacturing and industrialised construction methods. The public perception of modular construction is changing, but perhaps the greatest endorsement of the industry’s progress is that many people do not notice modular buildings at all. They simply see well-designed, functional, attractive spaces that allow businesses to operate, patients to receive care, students to learn and communities to thrive. The technology behind those buildings may be innovative, but the experience they provide is familiar. Modular buildings are already shaping the places where we live, work and spend our time but have simply been hiding in plain sight. Modular and Portable Building Association The MPBA is the UK’s leading trade body representing the modular and portable building sector. The association champions the benefits of volumetric construction, supporting its members in accelerating the growth and adoption of modular technology across the UK. Through advocacy, training, guidance and collaboration, the MPBA promotes best practice, quality standards and innovation across the industry, bringing together architects, engineers, manufacturers and supply chain partners to drive the sector forward. The MPBA is committed to advancing sustainable construction practices, raising professional standards and supporting the delivery of safe, efficient and high-quality modular solutions for the environments where people work, receive care, teach and learn. Find out more at: www.mpba.biz Building, Design & Construction Magazine | The Choice of Industry Professionals
Read More »
Government procurement simplification welcomed by Pagabo Group CEO

Government procurement simplification welcomed by Pagabo Group CEO

By Amman Boughan, CEO at Pagabo Group. Members of the new Labour cabinet are busy making their arrival known, with announcements coming thick and fast. Procurement has been a frequent talking point for prime minister Andy Burnham since his resurgence and rise to the top of government. However, talking is one thing and issuing a procurement policy note (PPN) is another. With that in mind, we wholeheartedly welcome and are encouraged by the direction of travel that the government is embarking on with the announcement of PPN 026 – the social value model – this week. The direction of travel, to simplify the model, helps to cut the red tape that locks smaller firms out, and focuses squarely on jobs, skills and community impact, which is what the Pagabo Group has been championing for a decade across wider public procurement. Continued simplification of an industry that is often overcomplicated can unlock so much opportunity. As our strapline goes: ‘Simply better procurement.’   Our focus has always been on helping the public sector deliver outcomes faster and creating impact where communities need it most. The government wants to back British jobs and skills in every postcode, so that’s exactly what its new weighting in public contracts will help achieve. Though it’s vital that social value is measured and proven, not just promised, as we’ve been advancing through our digital operating system. We don’t have long to wait until the rules begin to apply and we stand ready to be a partner in leading the change that the government wants to see. Building, Design & Construction Magazine | The Choice of Industry Professionals
Read More »
7 Exciting Trends in Communal Area Design

7 Exciting Trends in Communal Area Design

Communal areas have become one of the most closely watched categories in commercial design. As organizations rethink how much space they need and what that space should do, shared lounges, break rooms and collaboration zones are being asked to work harder than ever. You’re no longer just planning a lunchroom or a lobby. You’re shaping the spaces that determine whether employees actually want to come into the office. For architects, designers and builders, this shift creates an opportunity to move past generic, one-size-fits-all layouts. Clients are asking harder questions about how a shared space will actually be used, who it needs to accommodate and how it will hold up over years of daily traffic. Below are seven trends currently shaping how communal areas are conceived, specified and built. 1. Biophilic Design and Natural Materials Natural light, greenery and organic textures continue to dominate communal area briefs. Designers are specifying white oak millwork, stone accents and living walls to soften the hard edges of commercial interiors and create a stronger sense of calm. This isn’t just an aesthetic preference. A systematic review of workplace stress research found that access to outdoor views and nature-based break areas measurably reduces employees’ stress response. Practically, this means larger glazing packages near shared spaces, operable skylights where structure allows and planting strategies that account for maintenance access. Teams should coordinate early with mechanical engineers, since additional glass and interior plantings can shift HVAC and humidity requirements across the entire zone. 2. Flexible, Multi-Functional Layouts The single-purpose break room is giving way to layered, adaptable spaces that can shift between quiet focus work, informal meetings and social gatherings throughout the day. Movable partitions, modular seating and furniture on casters let a communal area be reconfigured without a renovation. Building professionals should design the shell to support this flexibility from the outset. That means flush flooring transitions, ceiling grids that accommodate reconfigurable lighting and power and data distribution that isn’t tied to a fixed furniture plan. A space that can only function in one way will quickly age out of usefulness. 3. Elevated Break Rooms and Coffee Bars Workplace kitchens and pantries are being redesigned with the same intentionality as residential kitchens. Homeowners are increasingly carving out separate prep kitchens and sculleries to keep food prep and clutter out of the main gathering space, and that same logic is now shaping commercial break room layouts. For commercial teams, this means budgeting for higher-grade finishes and the plumbing and electrical capacity to support espresso equipment, filtered water systems and induction cooktops. 4. Smart Technology Integration Communal areas are increasingly wired for convenience, with technology built into the space rather than bolted on afterward. This trend places new demands on infrastructure planning. Low-voltage cabling, dedicated network drops and coordination with IT teams need to happen at the design stage, not as a retrofit once furniture is already selected. 5. Wellness-Focused Amenities Wellness has moved from an amenity add-on to a core design driver, and communal areas are where that shift shows up first. Communal areas now regularly include quiet rooms, meditation nooks and improved air filtration alongside the more familiar café and lounge functions. A Harvard-led study on office air quality linked low ventilation rates and elevated particulate matter to measurably reduced cognitive performance among office workers. Designers should treat air quality and acoustic privacy as measurable performance targets rather than vague goals, and document them the same way lighting levels or fire ratings would be documented in a project spec. 6. Acoustic Comfort and Zoning Open, social communal areas create an obvious tension. The same buzz that makes a space feel lively can also make it hard to concentrate or hold a private conversation. Noise-related dissatisfaction affects over half of open-plan office workers, making it the leading source of workplace complaints. This requires early collaboration between interior designers and acoustic consultants, particularly in buildings with hard, reflective surfaces like exposed concrete or large expanses of glass. 7. Sustainable and Low-Maintenance Finishes Durability and sustainability are converging in communal area material choices. Recycled quartz surfacing, responsibly sourced wood and low-VOC finishes are being specified not just for their environmental credentials but because they hold up better under heavy daily use than trend-driven alternatives that need frequent replacement. Building teams should weigh life cycle cost alongside up front price when selecting these materials, since a communal area with dozens of daily users will show wear far faster than a private office. Specifying finishes built for longevity now can prevent a costly refresh in just a few years. Designing Communal Areas That Last Communal area design has grown far more sophisticated than it was even a few years ago, drawing influence from hospitality, wellness and residential design in equal measure. The strongest projects treat these spaces as flexible, well-engineered environments rather than an afterthought tacked onto the end of a floor plan. Building design and construction professionals who plan for flexibility, air quality, acoustics and durable materials from the earliest stages will be best positioned to deliver communal areas that hold up to daily use and continue to serve occupants well past the initial move-in.

Read More »
What Goes Into Efficient Waste Management? Insights, Programs and More

What Goes Into Efficient Waste Management? Insights, Programs and More

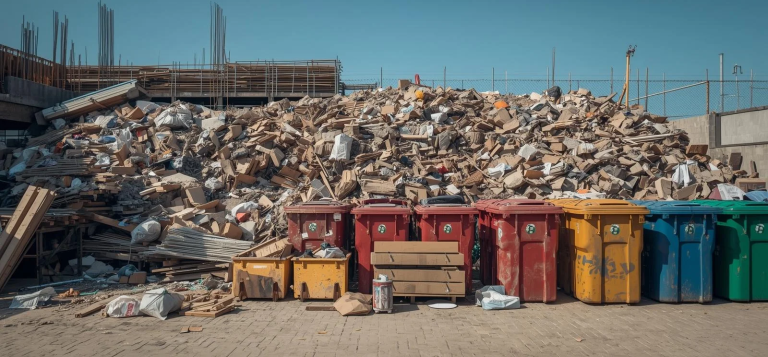
The sheer volume of waste the construction industry generates raises critical questions about efficient management practices. In response, building design and construction professionals are shifting away from reactive disposal toward digital waste management solutions that protect profit margins while improving operational efficiency. As companies evaluate how different waste management software options compare, understanding the total cost of this transition and the programs available remains essential for informed decision-making. The True Cost of Construction Waste Poor material management silently drains profits across the construction sector. Reliance on manual tracking and paper tickets results in significant financial losses that compound over time. The EPA estimates that construction and demolition debris accounts for over twice the amount of municipal solid waste generated in the United States. The financial impact extends beyond volume. Research indicates that 95% of delivery tickets and 75% of waste records contain incomplete or inaccurate information. These data gaps lead to billions in lost revenue across the industry. Manual processes fail to capture critical information about material flows, disposal costs and operational inefficiencies that erode project budgets. Proactive Management Boosts the Bottom Line Embracing operational excellence and digital tracking transforms waste management from a compliance burden into a profit-generating function. When companies reduce waste directly, associated costs drop proportionally. Rising hauling and landfill fees make this approach increasingly valuable for maintaining project profitability. Landfill costs continue climbing, with tipping fees rising about 4% year-on-year, based on the 2025 national average. Zero-waste approaches and digitally tracked operations help contractors preserve substantial portions of project budgets. Digital systems provide real-time visibility into waste streams, enabling companies to identify cost-saving opportunities and optimize disposal routes. The shift toward proactive management represents a strategic investment in long-term operational efficiency. How Do Different Waste Management Software Options Compare? Specialized software helps companies gain complete visibility over waste operations, streamline routing and ensure compliance. The following solutions offer distinct approaches to automated waste management for building design and construction professionals. 1. Paradigm Software L.L.C.® Paradigm Software L.L.C.®has been providing automated weighing and routing software solutions to recycling and roll-off businesses for more than three decades. Its WeighStation® solution offers a centralized system with flexible customization that enables efficient, fully unattended operations. The platform has processed 40 million transactions per year across 986 customer sites. Key features include: 2. ISB Global ISB Global offers solutions for companies seeking intelligent logistics automation on a global scale. Its Waste and Recycling One software adheres to digital waste tracking regulations in the United Kingdom. The platform delivers comprehensive control and ranks among the most advanced environmental waste management and recycling software available. Key features include: 3. Eco Software Solutions Eco Software Solutions presents a continuous-flow solution designed to eliminate duplicate data entry through EcoSoft. The platform adapts to existing work processes for smoother integration, aiming to reduce administrative overhead while enhancing waste management capabilities. Key features include: 4. The Access Group The Access Group has developed business management software for over 160,000 small and midsized organizations. Access Weighsoft Evo represents its modular solution tailored for construction aggregate and commercial waste management. The platform emphasizes seamless implementation and migration to minimize operational disruptions. Key features include: 5. Evreka Evreka delivers cloud-based waste management technology focused on smart city applications and sustainable operations. The platform combines Internet of Things sensors with artificial intelligence to optimize collection routes and reduce operational costs. Evreka serves municipalities and private waste operators seeking data-driven decision-making capabilities. Key features include: Frequently Asked Questions Building professionals often have questions about implementing efficient waste management systems. The following addresses common concerns. Q: What are the true costs of construction waste? A: The costs extend beyond disposal fees. Incomplete waste records and inaccurate tracking lead to billions in lost revenue across the industry. Manual systems fail to capture critical data about material flows, resulting in missed opportunities for cost reduction. Rising tipping fees compound these losses, with national averages increasing approximately 4% annually. Q: How does proactive management improve the bottom line? A: Digital tracking and operational excellence reduce expenses across multiple categories. Real-time visibility into waste streams enables companies to identify inefficiencies and optimize disposal routes. Reduced hauling costs, lower landfill fees and improved material recovery contribute directly to project profitability. These systems transform waste management from a cost center into a value-generating operation. Q: What features should building professionals look for in different waste management software options? A: Essential features include weighbridge integration for accurate transaction recording, route optimization to reduce transportation costs, and automated compliance tracking to ensure regulatory adherence. Robust reporting capabilities provide the insights needed for continuous improvement. End-to-end integration from weighing through invoicing eliminates manual data entry and associated errors. Strong technical support ensures operational continuity during implementation and daily use. Final Thoughts on Efficient Waste Management Transitioning to proactive waste tracking and leveraging specialized software makes waste management substantially more efficient. These practices and programs support circular economy principles while protecting profit margins. Building design and construction professionals who adopt digital solutions position their operations for sustainable growth and improved financial performance in an increasingly competitive market.

Read More »