
Holding the keys to your new home doesn’t mean you actually own it. Thousands of buyers move in, pay for repairs, and make monthly installments without holding official legal ownership—leaving their hard-earned equity completely unprotected if the contract sours.
Understanding how rights split between legal title and equitable title helps you spot predatory terms, hold sellers accountable, and secure your property rights. This guide breaks down what these ownership stakes mean so you can safeguard your investment long before signing on the dotted line.
Understanding Legal and Equitable Title
Holding legal title means your name is on the deed, granting you official, formal ownership of the property. Equitable title, on the other hand, gives you the legal right to acquire full ownership once you meet specific conditions, such as completing your contract payments. While equitable rights protect your financial stake before closing, they do not grant you unlimited freedom to sell, refinance, or make major changes to the home immediately.
This distinction is especially crucial in seller-financed transactions. In a contract for deed, the seller retains legal title until you pay off the balance in full, whereas a standard mortgage transfers title immediately and secures the loan against the home. Since every financing agreement carries different rules and risks, you should always clarify how your deal is structured before moving forward.
Know When Ownership Transfers
Your agreement should identify exactly when the seller must legally deliver the deed. In many alternative financing arrangements, the physical right to occupy a home and the formal record of ownership are split across a timeline.
When buyers move in before the deed is officially conveyed, understanding the difference between legal title and equitable title becomes vital to mapping out who holds what rights if a dispute arises. As detailed in legal analyses from Underwood Law Firm, P.C., these bifurcated rights dictate how courts view possession versus actual ownership when contracts run into trouble. For buyers, the critical question is always whether formal ownership transfers at closing or is withheld until the final installment is paid.
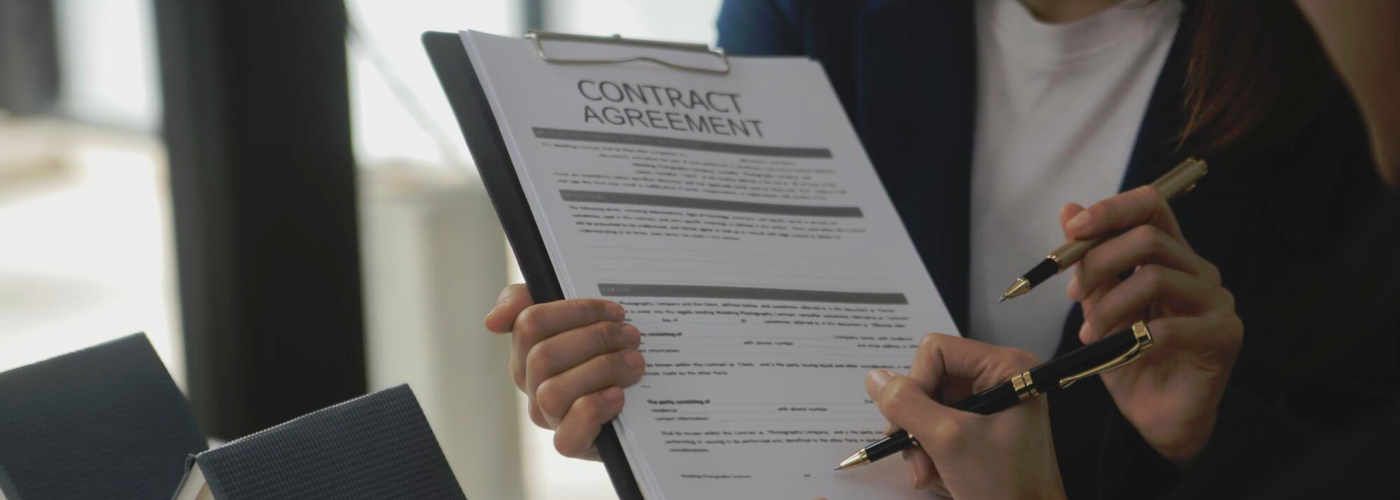
Do not rely on a seller’s verbal assurance that the property is “basically yours.” The written agreement should explicitly detail the transfer requirements and outline what happens if either party fails to perform.
Before signing, clarify three essential points:
- When the deed transfers
- Who pays property expenses
- What happens after missed payments
Also check whether the agreement requires a large final payment. Affordable monthly installments offer little reassurance if you cannot cover the remaining balance when it becomes due.
Check the Property and Paperwork
Simply getting the keys tells you very little about whether the seller can deliver a clean title. Hidden mortgages, back taxes, or competing legal claims can quickly derail your investment. Thoroughly investigating property records and contract terms before handing over substantial funds is essential.
Investigate Existing Title Problems
A professional title search uncovers recorded liens and hidden liabilities that could jeopardize your ownership. Before moving forward, insist on clear answers about how outstanding debts will be settled and whether a lender holds claims that could threaten the transaction. For additional context on policy protections, read the U.S. Department of the Treasury’s discussion of title insurance.
Consult your settlement officer to determine which policy covers your specific interests and what key exclusions might apply. Never assume that every potential ownership dispute is automatically covered by insurance. Resolving title issues before closing guarantees a much smoother path to full ownership.
Review Default and Transfer Terms
Your agreement must explicitly define payment deadlines, maintenance responsibilities, tax obligations, and the exact deed transfer process. Clear, unambiguous language prevents costly misunderstandings over duties down the road. Vague contract terms leave room for conflicting interpretations between buyer and seller.
Pay extra attention to default provisions in the contract. Confirm whether you are guaranteed advance notice and a grace period to cure missed payments. Finally, consult a real estate attorney to evaluate how local forfeiture laws apply to your situation.
Recognize the Risks of Delayed Title
Postponing formal ownership carries significant financial exposure that many buyers fail to anticipate. According to research by The Pew Charitable Trusts, roughly 1.4 million Americans relied on land contracts in 2022. Understanding the potential downsides of these seller-financed deals ensures you protect your hard-earned equity before moving in.
Before signing, evaluate these critical financial vulnerabilities:
- Sudden loss of invested capital
- Unexpected seller mortgage defaults
- Unrecoverable home repair expenses
- Severe immediate forfeiture penalties
Consulting a qualified real estate attorney ensures you know exactly which funds you can legally recover if the deal falls through early. Having an expert review your options beforehand safeguards your financial stability throughout the entire homebuying process.
Secure Your Path to Property Ownership
Navigating legal and equitable title requires careful attention to every detail of your purchase agreement. Confirming deed transfer terms, verifying property records, and recognizing the risks of delayed ownership are essential steps to protect your investment.
Before signing any contract, consult an independent real estate attorney to review the paperwork. A thorough professional evaluation gives you clarity, protects your financial stake, and ensures a clear path to true homeownership.